Does Title Insurance Require a Notary at Closing?
Title insurance doesn't require a notary, but your lender and county recording law do. Here's who needs it and who pays the notary fee.
Written by: Terry May
NNA-Certified Loan Signing Agent | Mobile Notary Public — 25+ years in Ohio lending
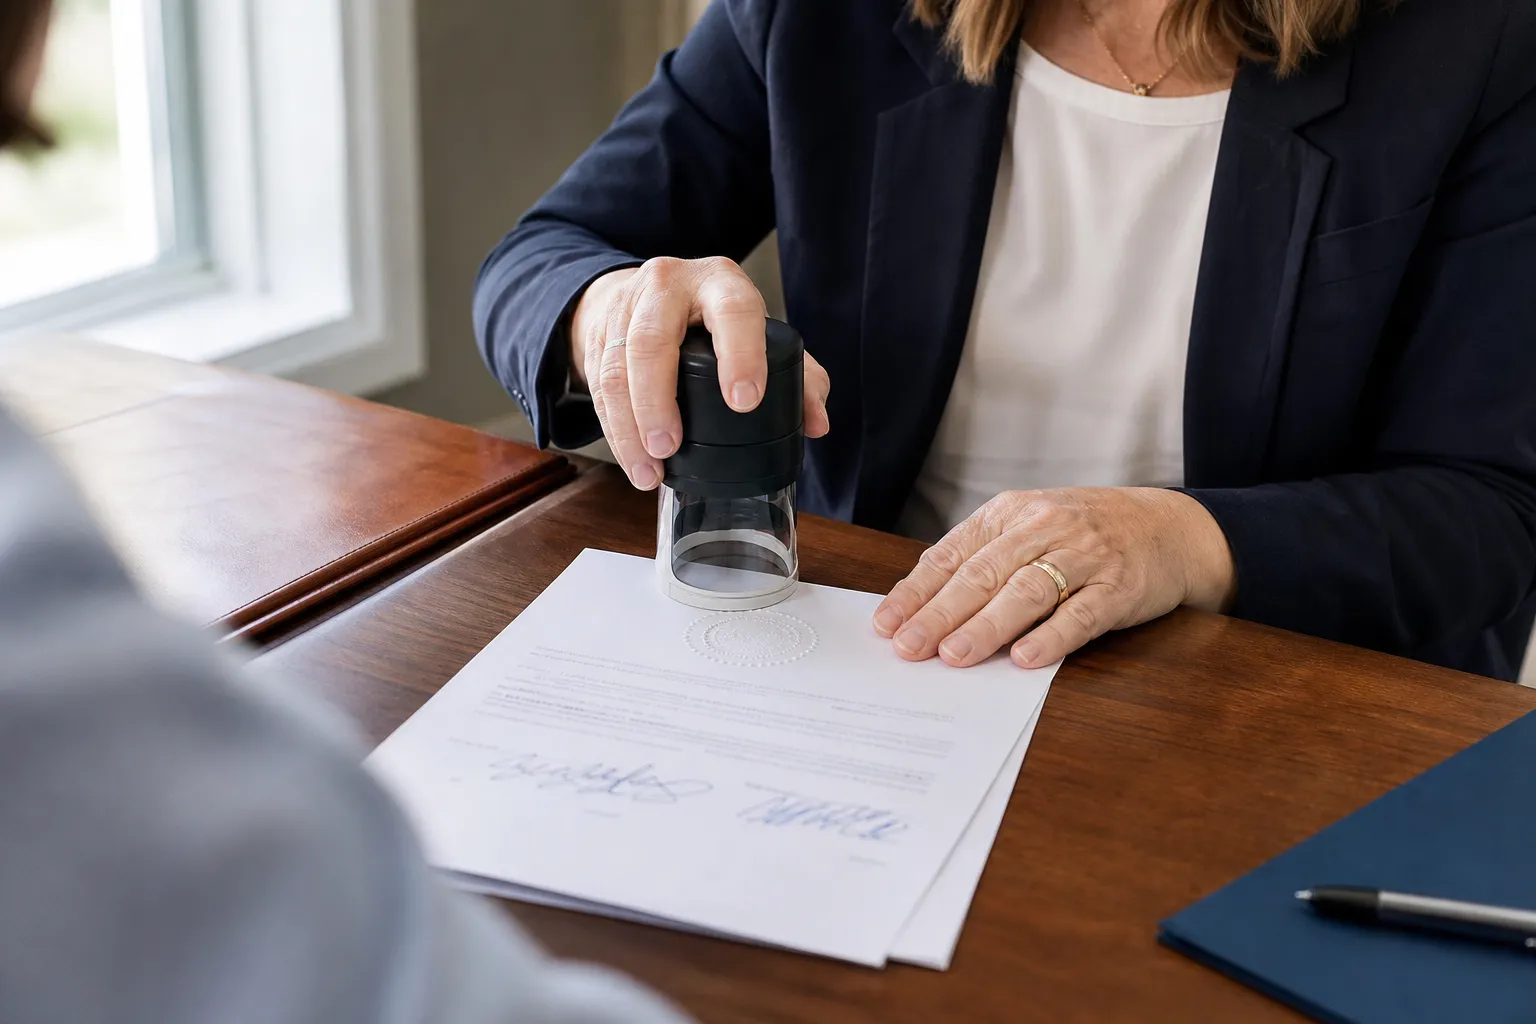
If you're a homeowner, real estate buyer or seller, or someone refinancing in Southwest Ohio, you've probably spotted "notary" on your closing checklist and wondered who's demanding it and who pays. The short answer is that your title insurance policy doesn't require a notary, but the documents that let your sale or loan get recorded do. Here's exactly how that works and where the cost usually lands.
Key takeaways
- Title insurance itself does not require a notary. The notary requirement comes from the deed and mortgage needing to be notarized before the county recorder will accept them, plus your lender's own closing instructions.
- The person who orders the signing usually pays the notary fee, and for a home purchase or refinance that cost is almost always bundled into your closing costs rather than billed to you separately.
- Not every closing document gets notarized. In a typical Ohio closing, the deed, the mortgage, and a handful of sworn statements need a notary; most disclosures and the promissory note do not.
- A missing or botched notarization can stop your documents from recording, which can delay funding or hold up the transfer of ownership entirely.
Does title insurance require a notary at closing?
No. Title insurance does not require a notary to be present at your closing, and nothing in your title policy hinges on who notarized your paperwork. Title insurance protects you and your lender against defects in the chain of ownership: unpaid liens, forged past deeds, missed heirs, clerical errors in old records. It's a safeguard on the history of the property, not a rule about signing day.
The confusion is understandable, because the title or escrow company is often the same office that schedules your notary or sends out a mobile signing agent. Two different things are happening in that room at once: the title company is confirming clean ownership, and a notary is verifying that the people signing are who they say they are. One service doesn't require the other. You can hold a title policy with no notary involved on the day, and you can have a notary present at a cash sale with no title insurance at all.
Chron's guide to notary signing agents and title agents lays out why the roles get mixed up: a signing agent is a commissioned notary trained to walk borrowers through loan paperwork, while the title agent handles the policy and the escrow. The same person sometimes wears both hats, but the hats aren't the same. You can read that breakdown in Chron's comparison of the two roles.
Why does your lender need a notary at closing?
Your lender needs a notary because the mortgage (or deed of trust) has to be notarized before it can be recorded against the property, and an unrecorded mortgage doesn't fully secure the loan. When you borrow money to buy or refinance, the lender takes a lien on your home. That lien only becomes public record, and legally enforceable against later claims, once the signed mortgage is filed with the county recorder. Recorders will not accept a mortgage that isn't properly notarized.
So the real source of the "notary required" line on your closing packet is two-fold:
- County recording law, which requires certain real estate instruments to carry a notary's acknowledgment before they're accepted for filing.
- Your lender's closing instructions, which spell out exactly which signatures must be witnessed and notarized so the loan can be sold, insured, or funded.
Title insurance is generally required by the lender whenever there's a mortgage involved, but that's a separate box the lender checks. Note one exception worth knowing: HUD's loan closing rules for FHA-insured mortgages state that title insurance is not mandatory at closing for those loans, even though the lender still has to be able to convey good title if a claim ever arises. You can see that in HUD's loan closing and insurance chapter. The notary piece, though, still applies to the deed and mortgage regardless of loan type.
If you're refinancing, the same logic holds, and the stakes on getting the notarization right are just as high. I've written up the mistakes I see most often on refis and HELOCs in common refinance and HELOC notary errors, because a single mismatched name or wrong date can send a package back.
Which closing documents actually have to be notarized?
Only a specific group of documents at a closing needs a notary, not the whole stack. In a typical Ohio home purchase or refinance, you'll sign dozens of pages, and most of them are disclosures, acknowledgments, and figures you're simply confirming. The ones that carry a notary block are the instruments that get recorded or sworn.
| Document | Notarized? | Why |
|---|---|---|
| Deed (warranty, quitclaim, survivorship) | Yes | Must be notarized to record the transfer of ownership |
| Mortgage / deed of trust | Yes | Must be notarized to record the lender's lien |
| Signature / name affidavit | Usually | Sworn statement confirming identity and name variations |
| Occupancy or owner's affidavit | Usually | Sworn statement the recorder or lender relies on |
| Power of attorney (if someone signs for you) | Yes | Must be notarized and often recorded |
| Promissory note | No | A contract between you and the lender, not recorded |
| Closing disclosure / settlement statement | No | A disclosure of figures, not a sworn document |
| Loan disclosures and acknowledgments | No | You're confirming receipt, not swearing an oath |
The exact list varies by transaction, by lender, and by whether you're the buyer, the seller, or refinancing. Sellers often have the lightest notary load, mostly the deed and a couple of affidavits. If you're the one selling, I've put together what to bring and expect in a guide to seller closing day.
Who pays for the notary at a real estate closing?
The party who orders the signing is the one who pays the notary, and in a financed home purchase or refinance that almost always means the fee is folded into your closing costs rather than handed to you as a separate bill. When the title or escrow company arranges the notary, the charge shows up as a line item in your settlement, often labeled a "signing fee," "notary fee," or "closing fee."
Who ultimately absorbs it depends on how your contract and loan are structured:
- Buyer-paid: In many purchases the buyer covers the signing fee as part of their closing costs, since the buyer is the one taking out the loan that needs notarized, recorded documents.
- Seller-paid: Sellers sometimes pay for the notarization of the deed and their own affidavits, or agree to cover it as a negotiated concession.
- Split or lender-credited: On a refinance, the fee is usually the borrower's, but it can be offset by a lender credit.
- Direct-pay: When you hire a mobile notary yourself (say, for a single document, a power of attorney, or an out-of-office signing), you pay the notary directly.
If you're booking me directly for a mobile signing rather than going through an escrow line item, I keep payment simple: cash, Venmo, or Zelle. Travel to you is part of what a mobile notary does, and I've explained how notary and travel fees work in Ohio in what you'll actually pay for a mobile notary. One honest note: a notary's actual per-signature fee is small and regulated; most of what you see on a closing statement is the convenience of having a trained signing agent come to you and handle the whole package correctly.
What happens if the notarization is missing or wrong?
A missing or defective notarization can stop your documents from recording, and that can hold up funding or the transfer of ownership until it's fixed. This is the quiet risk buyers and sellers underestimate. The signing can feel finished, everyone shakes hands, and then days later the recorder rejects the package because a notary block was left blank, a date was wrong, or a name didn't match the identification.
Common problems I catch before they become delays:
- The signer's name on the ID doesn't match the name typed on the deed or mortgage.
- The notary certificate is missing the venue (the county and state), the date, or the expiration.
- Someone signs under a power of attorney that itself wasn't properly notarized.
- Initials or a signature are missing on a page the lender flagged as required.
Getting these right the first time is the entire job. As a mobile loan signing agent working across Southwest Ohio, I'm NNA Certified, carry a 2 million dollar errors and omissions policy, complete a yearly background screening, and have been doing this for 7 years. That combination is what most lenders and title companies require of a signing agent before they'll send a package to your door. You can see the full scope of what a closing signing involves on my loan signing services page.
Because I offer same-day service, I can also step in when a signing falls apart at the last minute: a signer in the hospital, a title that needs a bedside or facility visit, or a package that has to be re-signed before funding. If that's where you are right now, call 513-226-9052 or book a signing.
Frequently asked questions
Does homeowners title insurance require a notary to be present at closing?
No. Homeowners title insurance protects you against defects in the property's ownership history and does not require a notary at closing. The notary requirement at a real estate closing comes from the county recorder needing notarized deeds and mortgages, and from your lender's closing instructions, which are separate from your title policy.
Who pays for the notary when you buy or refinance a home?
The party who orders the signing pays, and in a financed purchase or refinance that fee is usually bundled into your closing costs rather than billed separately. Depending on your contract, the buyer, the seller, or a lender credit can cover it. If you hire a mobile notary directly for a specific document, you pay the notary at the signing.
What documents at a home closing have to be notarized?
In a typical Ohio closing, the deed, the mortgage or deed of trust, any power of attorney, and certain sworn affidavits (like a name or occupancy affidavit) must be notarized because they're recorded or sworn. Most other pages, including the promissory note, the closing disclosure, and loan acknowledgments, do not need a notary.
Can a mobile notary come to my home or hospital for a closing in Southwest Ohio?
Yes. I'm a mobile loan signing agent serving Southwest Ohio, and I travel to homes, offices, hospitals, nursing homes, and bedsides for closings and single-document signings. I offer same-day service, so if a signing needs to happen quickly, call 513-226-9052 or book online.
Before We Arrive
Bring your document unsigned and a valid government-issued photo ID. If witnesses are required, we will let you know when you schedule.
We serve homes, offices, hospitals, and care facilities throughout Southwest Ohio — Warren, Hamilton, Butler, Montgomery, Greene, and Clinton counties. Same-day appointments are typically available across the Cincinnati-Dayton metro.
Need a notary today?
We come to you — same-day available throughout Southwest Ohio.
25+ years in commercial and residential lending. Mobile notary serving Warren, Greene, Clinton, Butler, Hamilton, and Montgomery counties. Background screened, E&O insured, and impartial witness only — no legal advice.
Last reviewed